📊 Key Takeaways of the 15-15-15 SIP Rule
- The Crorepati Formula: ₹15,000/month for 15 years @ 15% CAGR = ₹1,00,27,601 (₹1.00 Crore).
- Compounding Dominance: Out of ₹1 Crore, your actual deposit is just ₹27 Lakh, while ₹73.3 Lakh (73%) is pure compounding gain.
- The Step-Up Alternative: Students can start with ₹7,500/month and a 10% annual salary step-up to achieve ₹1.02 Crore by Year 15.
- Avoid Regular Plans: Choosing Direct-Growth plans saves you up to ₹12.4 Lakh in lost distributor commissions over 15 years.
In India’s financial circles, reaching your “First Crore” is considered the golden milestone of wealth creation. For a college student, intern, or first-time corporate employee, ₹1,00,00,000 looks like an impossible fantasy.
Yet, the mathematics of systematic mutual fund investing proves that you don’t need an inheritance, lottery ticket, or risky crypto gambles to become a Crorepati. You just need discipline, consistency, and a fundamental understanding of the 15-15-15 Rule.
In this guide, we break down how the math works, the realistic assumptions behind the 15% return rate, the silent commission traps of regular plans, and how students can adapt this formula starting with as little as ₹2,000 or ₹5,000 per month using modern Step-Up SIP strategies.
Interactive Simulation: Test Your Personal Crorepati Timeline
Don’t just calculate with fixed formulas. Try our free step-up SIP calculator with inflation to model custom monthly deposits (from ₹500 stipend to ₹50,000), toggle 5% to 15% annual step-ups, and project your post-tax maturity corpus in real-time.
The 15-15-15 Rule Explained: The Math Behind the First Crore
The rule is built upon three simple numbers:
- 15: Monthly Investment Amount = ₹15,000 per month
- 15: Investment Tenure = 15 Years (180 months)
- 15: Expected Annual Rate of Return = 15% CAGR
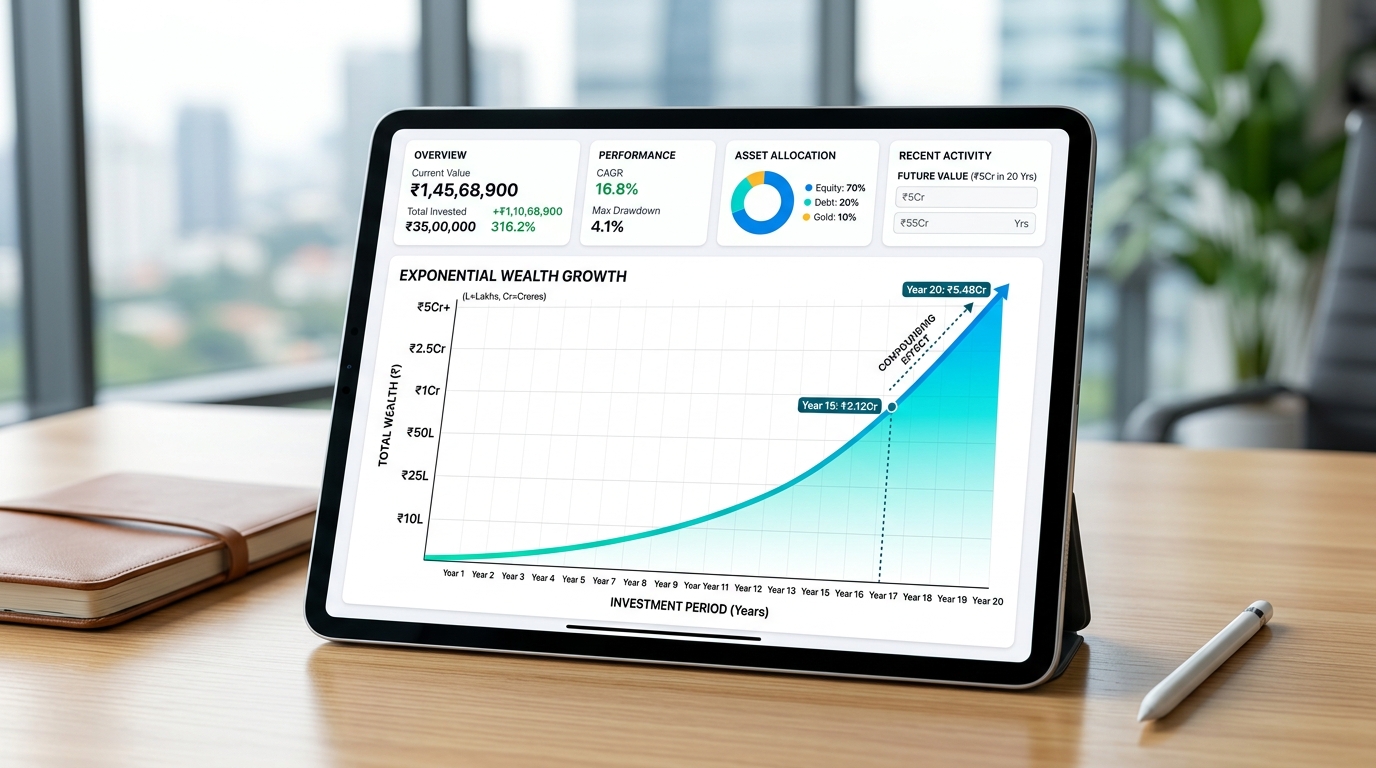
TeenBucks Guide: Notice how compounding gains account for over 73% of your final accumulated corpus
Using the standard compound interest annuity formula:
Where P = ₹15,000 | i = 15%/12 = 0.0125 | n = 180 months
Final Maturity Corpus = ₹1,00,27,601 (~₹1 Crore)
Look at the stunning asymmetry of this result:
- Total Money Deposited: ₹15,000 × 180 = ₹27,00,000 (27%)
- Compounded Wealth Gain: ₹73,27,601 (73%)
- Wealth Multiplier: 3.71x of invested capital
Is a 15% Return Realistic in India? (The Honest Truth)
While 15% CAGR makes the rule memorable, young investors must understand market realities:
- Nifty 50 Index (Large Cap): Historically delivers approximately 12% to 13% CAGR over long horizons. At 12%, a ₹15,000/month SIP for 15 years yields ₹75.14 Lakh (not ₹1 Crore).
- Flexi-Cap & Mid-Cap Funds: High-performing active funds (such as Parag Parikh Flexi Cap, HDFC Mid-Cap Opportunities, and Nippon India Growth) have delivered 15% to 18% over historical 15-year periods according to data published by AMFI (Association of Mutual Funds in India).
If you want to achieve ₹1 Crore strictly with conservative 12% returns, you have two simple choices:
- Increase your monthly deposit to ₹20,000/month for 15 years.
- Or let your investment compound for 18 years instead of 15 years.
To calculate your exact personal number under any return rate, open the 🎯 Target Goal mode in our SIP calculator for college students India.
The Extended Compounding Horizon: 15-15-15 vs 15-15-20 vs 15-15-30
What happens if you don’t cash out at year 15? The true miracle of compounding reveals itself when you leave the money untouched. Look at how wealth explodes across decades when investing the same ₹15,000/month at 15% CAGR:
| Time Horizon | Total Invested (₹) | Estimated Corpus @ 12% | Estimated Corpus @ 15% | Wealth Multiplier |
|---|---|---|---|---|
| 10 Years | ₹18,00,000 | ₹34,85,085 | ₹41,79,859 | 2.32x |
| 15 Years (15-15-15) | ₹27,00,000 | ₹75,13,741 | ₹1,00,27,601 (~₹1.00 Cr) | 3.71x |
| 20 Years | ₹36,00,000 | ₹1,49,87,220 | ₹2,27,38,725 (~₹2.27 Cr) | 6.32x |
| 25 Years | ₹45,00,000 | ₹2,84,36,344 | ₹4,87,00,750 (~₹4.87 Cr) | 10.82x |
| 30 Years (15-15-30) | ₹54,00,000 | ₹5,24,24,463 | ₹10,51,47,305 (~₹10.51 Cr!) | 19.47x |
Notice how between Year 15 and Year 30, your invested capital merely doubles from ₹27 Lakh to ₹54 Lakh—yet your total wealth multiplies more than tenfold from ₹1 Crore to over ₹10.5 Crore! That is the back-heavy nature of compound interest.
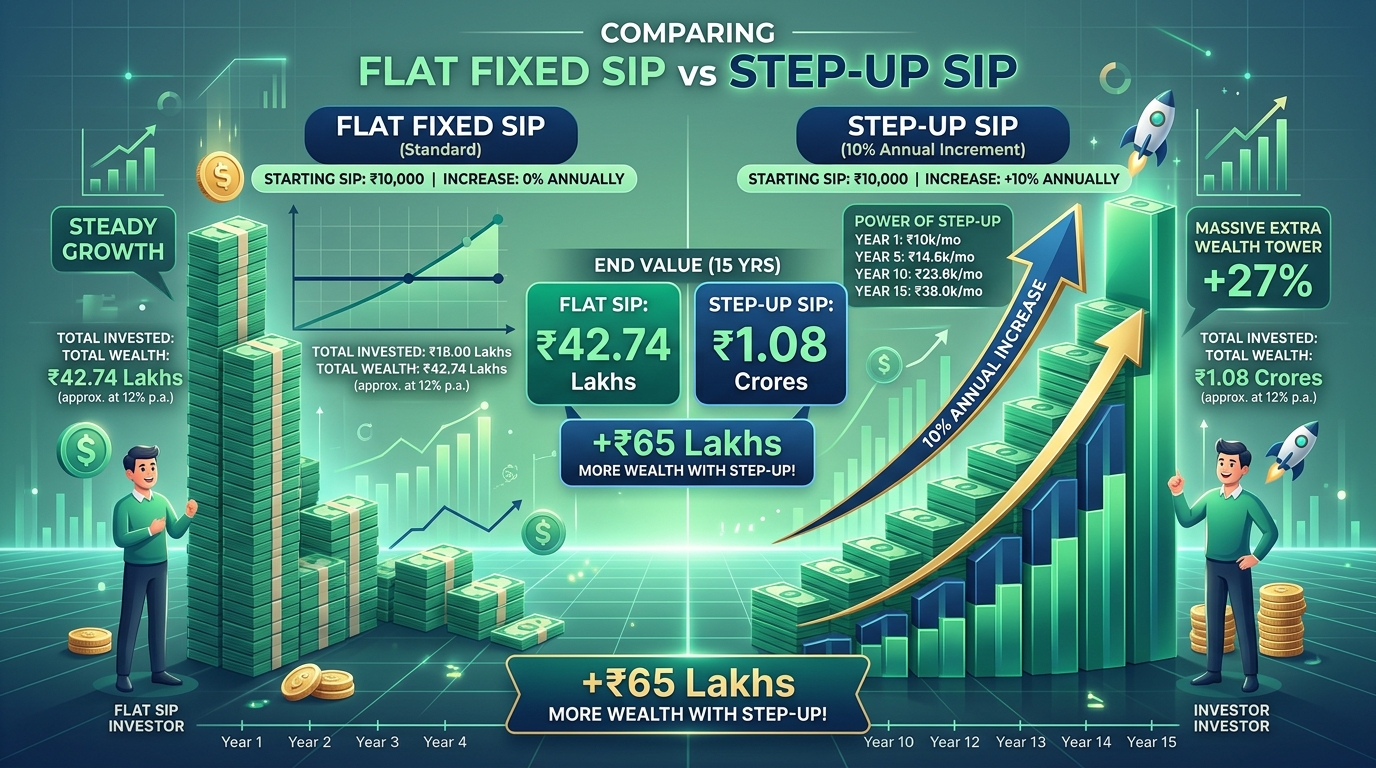
TeenBucks Guide: Starting at ₹7,500 and stepping up by 10% annually outperforms a flat ₹10,000 SIP
The Student Adaptation: The 10% Step-Up Route to ₹1 Crore
Most college students or 21-year-old interns cannot afford ₹15,000 per month right out of the gate. But here is the secret that banking relationship managers never explain: You don’t need ₹15,000 today if you use a Step-Up SIP.
Suppose you start with just ₹7,500 per month (half the traditional rule) at age 22, and you increase your monthly investment by 10% every year as your salary increases:
| Year | Monthly SIP (₹) | Yearly Deposit (₹) | Estimated Portfolio Value @ 13% |
|---|---|---|---|
| Year 1 | ₹7,500/mo | ₹90,000 | ₹96,500 |
| Year 5 | ₹10,980/mo | ₹1,31,760 | ₹8,35,000 |
| Year 10 | ₹17,685/mo | ₹2,12,220 | ₹30,40,000 |
| Year 15 | ₹28,480/mo | ₹3,41,760 | ₹1,02,40,000 (~₹1.02 Crore!) |
By starting at an achievable ₹7,500 and letting your raises fund the step-up, you still hit the ₹1 Crore milestone by Year 15 without ever sacrificing your student lifestyle.
The Direct Plan vs Regular Plan Trap: Don’t Lose ₹22.4 Lakh in Commission
One of the biggest mistakes college students make is walking into a bank branch and letting a relationship manager open a mutual fund account. Banks sell Regular Plans, which silently deduct a 1.0% to 1.5% annual distributor commission from your total fund value.
To understand how lethal this 1.25% fee is over 15 years on a ₹15,000/month SIP:
- Direct Plan (15% Net Return): Final Corpus = ₹1,00,27,601
- Regular Plan (13.75% Net Return): Final Corpus = ₹87,85,420
- Hidden Commission Loss to Distributor: ₹12,42,181 lost forever!
Over a 20-year horizon, that same 1.25% commission leak robs you of over ₹38,00,000! Always ensure your fund name includes the magic word “Direct – Growth”. To pick the right zero-commission investing app, read our exhaustive breakdown on Best Zero-Fee Demat Accounts for College Students in India (Groww vs Zerodha Hidden AMC Exposed).
The Ideal Portfolio Blueprint to Target 15% CAGR
Under SEBI (Securities and Exchange Board of India) mutual fund categorization guidelines, no single scheme guarantees 15%. To build a durable portfolio capable of achieving 14% to 16% CAGR through bull and bear markets, diversify across three complementary asset classes:
- 50% in Nifty 50 Index Fund (Large Cap): e.g., UTI or HDFC Nifty 50 Index Fund. Allocating ₹7,500 here gives you ownership in India’s top 50 corporate giants (Reliance, TCS, HDFC Bank) with razor-thin expense ratios (0.06% to 0.10%). Expected return: 12% to 13%.
- 30% in Flexi-Cap Fund: e.g., Parag Parikh Flexi Cap Fund. Allocating ₹4,500 allows professional fund managers to dynamically pivot between large, mid, and small-cap stocks. Expected return: 14% to 16%.
- 20% in Mid-Cap Fund: e.g., Motilal Oswal or HDFC Mid-Cap Opportunities Fund. Allocating ₹3,000 captures India’s high-octane emerging sector leaders. Expected return: 16% to 18%.
TeenBucks Guide: Setting up a 100% paperless Direct-Growth SIP mandate on your phone takes less than 15 minutes
The Inflation Reality Check: What Will ₹1 Crore Be Worth in 15 Years?
At TeenBucks, we believe in radical financial honesty. One crucial factor that motivational reels ignore is inflation.
Assuming an average annual inflation rate of 6% in India (matching the Reserve Bank of India’s upper tolerance threshold), ₹1 Crore in 15 years will have the purchasing power of approximately ₹41.7 Lakh in today’s money.
While ₹41.7 Lakh is still a formidable financial cushion, it means your true long-term goal should ideally be ₹2.5 Crore to ₹3 Crore if you want ₹1 Crore of equivalent purchasing power. This is why continuing your SIP beyond 15 years—into years 18 to 25—is where unimaginable, multi-generational wealth is forged.
Taxation on ₹1 Crore Corpus: Budget 2024–2026 Section 112A Rules
Under the revised capital gains tax regime enacted by the Income Tax Department under Section 112A:
- Long-Term Capital Gains (LTCG): Applies to units held longer than 12 months. Gains up to ₹1.25 Lakh per financial year are 100% tax-free. Gains above ₹1.25 Lakh are taxed at 12.5%.
- The Tax Harvesting Hack: Students can legally save tens of thousands in taxes by practicing annual tax-gain harvesting. Every March, redeem units with up to ₹1.25 Lakh of profit tax-free, and immediately repurchase the same units on the next trading day. This resets your purchase cost base higher and prevents massive lump-sum tax bills upon final maturity!
The Harvest Phase: How to Live Off ₹1 Crore Using SWP
Once you achieve your ₹1 Crore target, do not redeem everything to pay 12.5% tax in one lump sum or deposit it in low-interest fixed deposits. Instead, activate a Systematic Withdrawal Plan (SWP).
By moving your ₹1 Crore into a conservative equity savings fund earning 8% to 10% annual returns, you can safely withdraw ₹60,000 to ₹75,000 every single month as passive income, while your principal corpus remains intact and continues outgrowing inflation.
Plan your monthly retirement cash flow using our free TeenBucks SWP Calculator to simulate safe withdrawal rates without ever depleting your capital. And if you ever need emergency cash before maturity, compare loan interest costs on our TeenBucks Loan & EMI Calculator rather than prematurely breaking your compounding engine.
Frequently Asked Questions: The 15-15-15 SIP Rule
What is the 15-15-15 rule in mutual funds?
The 15-15-15 rule is a personal finance guideline stating that investing ₹15,000 every month for 15 years at an expected compound return of 15% per annum creates an accumulated corpus of over ₹1 Crore (₹1,00,27,601). Out of this, ₹27 Lakh is your deposited capital, and ₹73.3 Lakh is generated through compound interest.
What is the 15-15-30 rule?
The 15-15-30 rule takes the 15-15-15 concept and doubles the time horizon. If you invest ₹15,000 per month at 15% returns for 30 years, your final wealth explodes from ₹1 Crore to an astonishing ₹10.51 Crore! This demonstrates how compounding accelerates exponentially in the final decade.
What happens if my mutual fund returns only 12% instead of 15%?
At a conservative 12% annual return, a ₹15,000/month SIP for 15 years accumulates to approximately ₹75.14 Lakh. To still hit ₹1 Crore in 15 years at 12%, you simply need to invest approximately ₹20,000 per month, or enable a 10% annual Step-Up starting at ₹10,500/month.