💡 Quick Answer: If a UPI transfer fails after your bank is debited and the receiver is not credited, RBI’s reversal deadline is generally T+1 calendar day. For a failed merchant payment with no confirmation at the shop, it’s T+5 calendar days. Eligible delays beyond these deadlines attract ₹100 per day in compensation. Check the status before making a second payment.
You’re at the college canteen. Four friends split lunch, you scan the QR and pay ₹450. Money disappears from your bank account. The UPI app says Pending. Canteen uncle says, “Payment nahi aaya. Ek baar aur karo.”
Now what? Pay again and risk losing ₹900? Or argue about a transaction neither of you can see properly?
First: don’t pay twice blindly. Check the transaction in your UPI app and bank account, note the reference number, and ask the merchant to check their payment status. A pending payment can still settle.
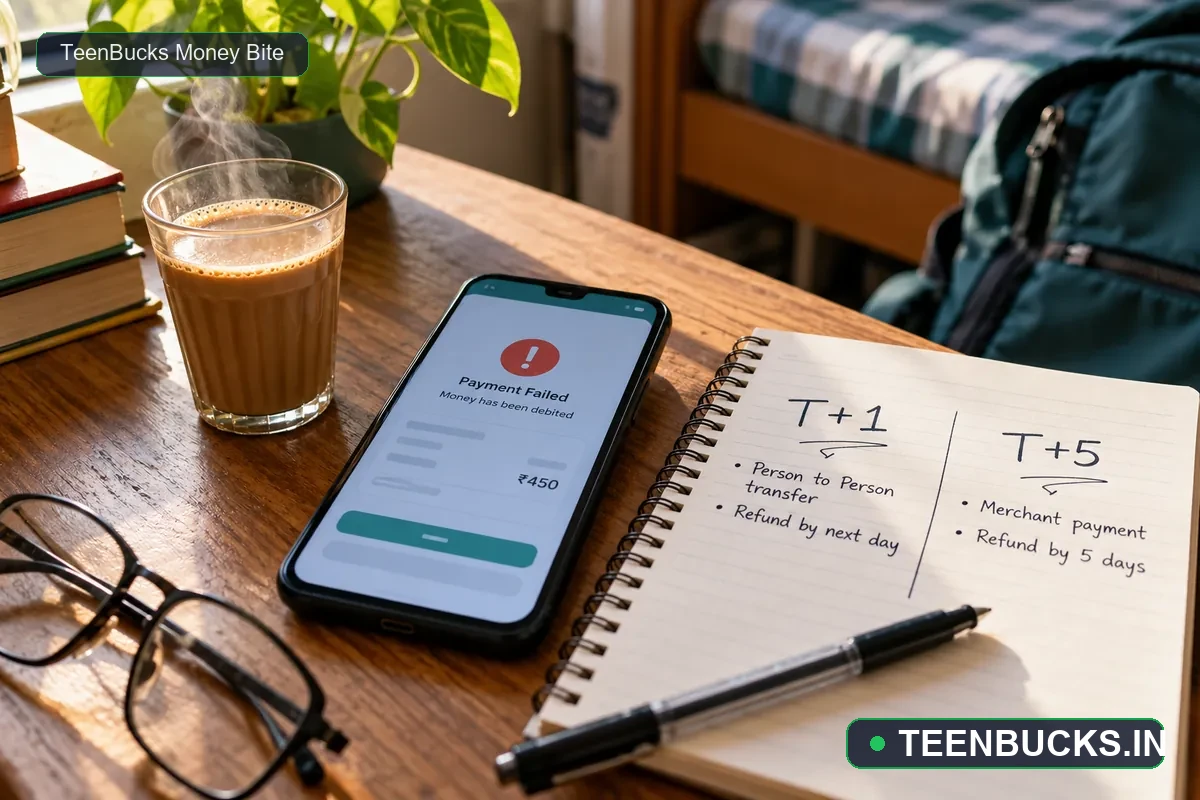
RBI’s actual refund deadlines: T+1 versus T+5
These aren’t promises from GPay or PhonePe. They’re from the RBI’s official failed-transaction circular.
| What went wrong? | RBI deadline | Compensation for eligible delay |
|---|---|---|
| You sent money to a friend; your account was debited, but theirs was not credited. | T+1 day | ₹100 per day beyond T+1 |
| You paid a merchant QR; your account was debited, but the merchant received no transaction confirmation. | T+5 days | ₹100 per day beyond T+5 |
T is the transaction date, and these are calendar days, not business days. The deadlines are outer limits; a reversal can arrive sooner. The rules cover qualifying failed domestic transactions, not every refund or disputed purchase.
The ₹100-per-day maths most people miss
Say you send ₹700 to your hostel roommate on Monday, 26 October. Your bank is debited, but their account never receives it, and the transfer fails.
- Monday: Transaction date (T).
- Tuesday: T+1; the eligible failed transfer should be reversed by this deadline.
- Thursday: The reversal finally happens.
That’s two days beyond the deadline × ₹100 = ₹200 in prescribed compensation for the qualifying delay. The original ₹700 reversal is separate from that ₹200. RBI says applicable compensation should be credited automatically, without waiting for a claim.
Money still missing? Do these three things
- Save proof now. Screenshot the status, debit entry, date, amount and UPI transaction reference/UTR/RRN. Don’t share your UPI PIN or OTP with “refund agents.”
- Raise a dispute. Use the transaction’s Help / Report an issue option in your UPI app and lodge a complaint with your bank. Keep the complaint number. NPCI’s complaint portal can also help route an eligible transaction complaint.
- Escalate if unresolved. If the reversal deadline passes, ask the bank about the missing refund and compensation. If you’re dissatisfied with its response, or there’s no response within the applicable deadline, consider the RBI Complaint Management System under the 2026 Integrated Ombudsman Scheme. Under that scheme, the ordinary no-response waiting period is 30 days (or a longer period required by applicable RBI/NPCI/card-network guidelines); follow its filing requirements.
One big difference: A payment that succeeded to the wrong UPI ID isn’t the same as a failed payment. And if a shop got the money but never delivered your order, that’s a different dispute too. Don’t automatically apply the ₹100 rule to either.
The TeenBucks takeaway: Before you scan twice, check twice. Your transaction reference matters more than the “Payment failed” screenshot somebody sends you. And if a stranger asks for your PIN to “release” a refund, read our fake UPI credit scam guide first.
Official sources: RBI failed-transaction circular (20 September 2019) · NPCI complaint portal · RBI Ombudsman FAQs (2026)
FAQs: UPI Failed Payment Refunds
1. Will my failed UPI transaction refund automatically?
For a qualifying failed transaction, RBI requires auto-reversal within the applicable T+1 or T+5 deadline. Still check the bank statement and raise a complaint if it doesn’t arrive.
2. Do I have to claim the ₹100-per-day compensation?
Under RBI’s framework, applicable compensation is supposed to be credited automatically. If it’s missing after a late reversal, use your transaction and complaint references to ask the bank to investigate.
3. What if I transferred money to the wrong person and it says “Successful”?
That’s not the failed-transaction scenario covered by these deadlines. Contact your bank and raise a UPI dispute promptly; recovery is not guaranteed.